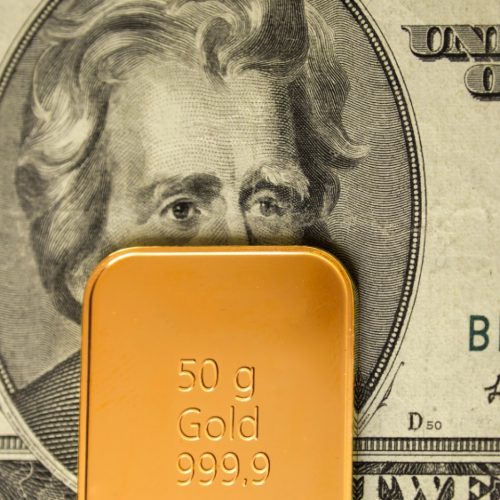
Gold futures fell three sessions in a row after Federal Reserve Chairwoman Janet Yellen’s semi-annual testimony last Tuesday, July 15.
Overall, Yellen’s comments to the United States Senate were “dovish” in nature, warning against spiking interest rates on the back of sooner-than-expected employment gains.
“If the labor market continues to improve more quickly than anticipated by the Committee, resulting in faster convergence toward our dual objectives, then increases in the federal funds rate target likely would occur sooner and be more rapid than currently envisioned,” Yellen said.
Yet Yellen seemingly took a contradictory stance later when she stated that slow wage growth indicated that there is still a slack in the jobs market.
So Which Is It?
MarketWatch.com may have put it best: “In sum, her message appeared as contradictory and convoluted as any good economist’s.”
Good point.
Apparently the market has picked up on this confusion and reacted accordingly. But how should the average investor respond?
Interest Rates and the Gold Prices
Traditionally, the widely accepted view is that higher interest rates cause a fall in gold prices — and inversely, low rates increase gold prices.
Ultimately, this is due to the fact that the rising rates make interest-paying investments (like bonds and Treasury bills) more desirable, while storing physical commodities becomes less attractive.
However, experts caution investors against using nominal interest rates to predict gold prices alone, since other factors can overwhelm the effect of interest rates.
For example, in looking at long-term gold bull markets in the last 100 years, GoldSeek found that nominal interest rates trended downward in the bull market of the 1930s, upward in the 60s and 70s, and downward during the first decade of the current bull market.
Thus, history shows that gold bull markets can charge forward in both high and low-interest phases, suggesting that the long-term nominal interest rate trend is not as critical. In short, gold prices see gains from low interest rates, an increasing yield-spread (a steepening yield curve), and widening credit spreads — each of which can occur when nominal interest rates are on an upward or downward trend.
Likewise, while a growing labor market and economy typically has an inverse relationship with gold, driving gold prices down in the short term, it isn’t all bad news for precious metals.
For instance, other metals — like silver, platinum, and copper, which have high-volume industrial demand — actually benefit from the upticks in manufacturing, construction, engineering and other industries that prosper under a thriving economy.
This is the main value in diversifying with precious metal investments: to have a windfall when times are good and when times are bad.
At Provident Metals, we sell premium gold, silver, copper, diamond, platinum and palladium bullion at some of the most competitive prices on the market. Sign up for our free newsletter and to receive member-exclusive discounts!
Leave a comment below or check us out on Facebook, Twitter and Google+ today.



Leave a Reply